2026 Best Wholesale Fertilizer Distributors Worldwide

The 2026 Best Wholesale Fertilizer Distributors Worldwide guide examines suppliers shaping modern agricultural input markets. It focuses on product quality, distribution reach, technical support, and responsible business practices. Farmers and retailers need more than low prices. They need consistent nutrient analysis, secure packaging, dependable delivery, and clear documentation.

Charlotte Hebebrand, Director General of the International Fertilizer Association, has stated: “Fertilizers are essential for global food security.” That principle gives this topic practical importance. Reliable wholesale fertilizer distributors connect manufacturers with farms across different climates, crops, and supply chains. Their work may involve bulk urea, NPK blends, phosphate products, potash, and specialty fertilizers. Each category requires careful handling and accurate specifications.

The strongest distributors also explain application rates and storage conditions. They support soil testing instead of promoting careless overuse. Responsible advice matters. A shipment arriving late can disrupt planting schedules. A mislabeled product can damage crops and weaken buyer confidence. These risks deserve attention.

No global ranking is perfect. Regional regulations, freight costs, seasonal demand, and crop needs can change quickly. Some smaller distributors may offer better local service than larger companies. That point is easy to overlook. This guide therefore considers practical performance, not only company size. It reviews market reputation, sourcing transparency, customer experience, and long-term reliability. Readers should still verify certificates, contracts, and local compliance before purchasing.

2026 Best Wholesale Fertilizer Distributors Worldwide

Global Fertilizer Distribution: Market Scope and Industry Structure

2026 Best Wholesale Fertilizer Distributors Worldwide

Global fertilizer distribution is becoming more regional, data-driven, and risk-sensitive. The International Fertilizer Association’s 2024 Medium-Term Fertilizer Outlook expects global nutrient demand to recover gradually through 2028. Growth is linked to cereal production, soil nutrient depletion, and stronger farm output in emerging markets. However, demand does not move evenly. Asia remains a major consumption center, while Africa and parts of Latin America show significant long-term potential.

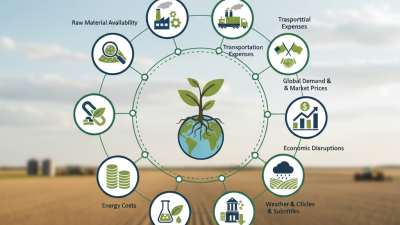
The structure is complex. Producers supply importers, port terminals, national wholesalers, cooperatives, and local retailers. Each layer affects price, delivery time, and product traceability. FAO’s 2024 Food Outlook highlights how energy costs, freight conditions, and fertilizer affordability influence food production. UN Comtrade data also shows that international fertilizer trade remains concentrated across several major exporting and importing corridors. That concentration creates efficiency, but it can also create vulnerability. One delayed vessel may disrupt a regional planting schedule. The map is not neat. Smaller distributors may know local soils better than large trading networks, yet often lack storage capacity and working capital.

Tips: Compare distributors by warehouse coverage, nutrient analysis, delivery records, and documentation quality. Ask for recent laboratory certificates. Review seasonal stock plans, not only quoted prices. The World Bank Commodity Markets Outlook can help buyers track fertilizer-related price pressure, but forecasts are not guarantees. A practical mistake is relying on one supplier. Dual sourcing may cost more, but it can protect farm operations when logistics change suddenly.

How to Evaluate Wholesale Fertilizer Distributors in 2026

Evaluating wholesale fertilizer distributors in 2026 requires more than comparing quoted prices. In field procurement, I have learned that a low offer can hide weak batch control, unclear freight terms, or costly delays. Start by checking legal registration, product specifications, safety documentation, and traceability records. Ask for a current certificate of analysis, not a generic brochure. It should show nutrient percentages, moisture, granulation, testing date, and laboratory details. Small gaps matter.

A reliable distributor should explain where each shipment is sourced, how it is stored, and how complaints are handled. Request a physical sample before signing a large contract. Examine particle consistency, packaging strength, labeling, and signs of moisture damage. Compare delivery performance using recent references, port records, and agreed lead times. Payment terms also deserve scrutiny. Check import rules, permitted nutrient limits, and labeling requirements in the destination market. Compliance is not optional.

Professional support separates a capable distributor from a simple reseller. Technical staff should recommend products by soil test, crop need, and application method, rather than promote the highest-margin item. Ask how shortages and rejected loads are managed. Their answer reveals operational maturity. Still, no evaluation method is perfect. References may be outdated, samples may not represent every batch, and forecasts can fail. Keep written acceptance criteria, inspect incoming cargo, and review performance after each delivery. Trust should be earned shipment by shipment.

Leading Fertilizer Distribution Regions and Supply Networks

In 2026, wholesale fertilizer distribution depends on regional access, storage capacity, and reliable transport links. Major supply networks connect producers with agricultural markets across Asia, Europe, North America, Latin America, and Africa. Coastal terminals often handle bulk shipments, while inland warehouses support smaller farm deliveries. Local distributors remain essential where roads, railways, or seasonal demand create delays.

Regional specialization shapes purchasing decisions. Southeast Asia requires steady deliveries for rice, palm, and horticultural production. European networks emphasize documented composition, traceability, and efficient cross-border movement. North American distributors often combine rail, river, and truck transport to serve large farming areas. In Africa, flexible packaging and nearby storage can matter more than shipment volume. Conditions vary sharply.

Good distributors provide batch records, safety documents, clear labeling, and realistic delivery schedules. They also monitor moisture, contamination risks, and warehouse ventilation. These details protect product quality during long storage periods. A strong supply network should include backup routes and transparent communication when ports or weather disrupt plans.

No network is flawless. Some suppliers promise speed but overlook the final inland delivery. Others maintain stock without checking local soil needs. Buyers should compare delivery history, storage practices, payment terms, and technical support before placing large orders. Reliable partnerships grow through evidence, not impressive claims.

2026 Best Wholesale Fertilizer Distributors Worldwide - Leading Fertilizer Distribution Regions and Supply Networks

Global wholesale distribution overview based on established production centers, import corridors, agricultural demand patterns, port infrastructure, and publicly available fertilizer trade data.

Distribution Region Regional Wholesale Role Main Fertilizer Categories Typical Supply Sources Key Distribution Corridors Primary Logistics Infrastructure Demand and Seasonality Wholesale Network Conditions 2026 Supply Outlook
East Asia High-capacity production and consumption region
Large domestic agricultural markets with significant nitrogen, phosphate, and compound fertilizer distribution.
Urea Ammonia MAP/DAP NPK Potash Domestic coal- and natural-gas-based nitrogen production; phosphate rock and potash imports; regional seaborne supply. Coastal production zones to inland agricultural provinces; major Asian sea lanes; river, rail, and truck distribution networks. Deep-water ports, bulk terminals, rail corridors, inland warehouses, river barges, and high-capacity bagging facilities. Strong demand before rice, wheat, maize, and vegetable planting periods; demand varies by monsoon and crop calendar. Highly developed wholesale markets, but exposed to energy prices, export policies, freight costs, and seasonal inventory cycles. Stable structural demand with continued emphasis on efficient nitrogen use, compound fertilizers, and lower-emission production.
South Asia Major import-dependent agricultural distribution market
Large seasonal demand supported by public procurement, cooperatives, and private wholesale channels.
Urea DAP MOP NPK Micronutrients Seaborne imports of nitrogen, phosphate, and potash products; selected domestic nitrogen and phosphate production. Indian Ocean import terminals to inland agricultural belts; coastal warehouses to rail-linked and truck-based distribution centers. Bulk ports, coastal storage, rail freight, trucking fleets, fertilizer warehouses, and extensive last-mile dealer networks. Demand peaks before monsoon planting and winter crop sowing; rice, wheat, cotton, sugarcane, and horticulture are major users. Large volume potential, strong policy influence, high sensitivity to import prices, currency movements, and port congestion. Demand is expected to remain substantial, while balanced nutrient use, localized production, and improved storage remain key priorities.
North America Integrated production, import, and export network
Strong nitrogen production base with major phosphate and potash distribution systems.
Anhydrous ammonia Urea UAN MAP/DAP Potash Domestic natural-gas-based nitrogen, domestic potash and phosphate resources, plus imported specialty and supplemental products. Gulf Coast and inland production to the Corn Belt and Great Plains; Canadian potash corridors to domestic and export markets. Pipeline systems, rail, inland waterways, river terminals, farm cooperatives, bulk blending plants, and covered storage. Very strong spring application season, with a secondary autumn demand period for winter crops and soil conditioning. Well-developed bulk handling and precision-agriculture systems; demand is highly influenced by crop margins and natural-gas costs. Reliable distribution capacity is expected, with growth in enhanced-efficiency products, digital inventory management, and nutrient optimization.
Latin America High-growth import and transshipment region
Large grain, oilseed, sugar, coffee, and plantation-crop markets generate strong wholesale demand.
Urea MAP/DAP Potash NPK Specialty blends Predominantly seaborne imports from major nitrogen, phosphate, and potash production areas; limited domestic production in selected countries. Atlantic import terminals to inland farming regions; river corridors and long-haul trucking routes serving major agricultural belts. Deep-water ports, bulk terminals, rail expansion, inland waterways, silos, blending plants, and regional dealer networks. Demand follows soybean, maize, wheat, sugarcane, and coffee planting cycles; crop calendars differ between northern and southern zones. Strong volume growth potential, but inland freight, port bottlenecks, currency volatility, and storage availability remain important constraints. Continued expansion of import terminals, rail-linked storage, localized blending, and customized nutrient products is likely.
Europe Mature regional distribution and blending market
Well-connected cross-border supply network with strong demand for regulated and efficiency-focused products.
Ammonium nitrate Urea UAN NPK Lime products Regional nitrogen and compound fertilizer production supplemented by imports of urea, phosphate, and potash products. North Sea, Baltic, Mediterranean, and Black Sea gateways to Central, Western, and Eastern European agricultural markets. Short-sea shipping, inland waterways, rail, truck fleets, port warehouses, bulk blenders, and regulated storage facilities. Main demand occurs before spring and autumn applications; weather, environmental rules, and energy prices strongly affect purchasing. Highly organized distribution, strict product and safety requirements, and increasing demand for nutrient-efficiency solutions. Market development is expected to focus on low-emission nitrogen, precision application, recycled nutrients, and improved supply resilience.
Middle East Major export-oriented production hub
Large-scale nitrogen and phosphate production supports global wholesale supply networks.
Urea Ammonia DAP/MAP Sulfur products Natural-gas-based nitrogen production and phosphate resources; strong reliance on maritime export channels. Red Sea, Arabian Gulf, Mediterranean, and Indian Ocean routes serving South Asia, Africa, Europe, and the Americas. Deep-water export ports, bulk-loading systems, industrial rail, storage terminals, and ship-to-ship or port-to-warehouse transfers. Domestic agricultural demand is more limited than export demand; international planting seasons drive shipment timing. Competitive production economics in selected hubs, with exposure to gas availability, maritime security, and freight conditions. Export capacity is expected to remain strategically important, with increasing attention to low-carbon ammonia and supply-chain diversification.
North Africa Phosphate-centered export and regional supply hub
Supports global phosphate fertilizer distribution and regional agricultural markets.
Phosphate rock DAP/MAP TSP NPK Ammonia Large phosphate resources and processing capacity; nitrogen inputs and ammonia may be produced locally or sourced internationally. Mediterranean and Atlantic ports to Europe, West Africa, Latin America, South Asia, and other import markets. Mining-to-port railways, bulk terminals, granulation plants, covered storage, and coastal export infrastructure. Regional demand follows cereal and irrigated-crop cycles; export shipments are distributed according to global planting seasons. Strong phosphate specialization, while nitrogen supply and energy availability can affect compound fertilizer output. Phosphate value chains, integrated processing, regional African distribution, and lower-carbon production are expected to expand.
Sub-Saharan Africa Underpenetrated growth market
Demand is expanding from a relatively low application base, with large differences among countries and farming systems.
Urea NPK DAP TSP Blended fertilizers Primarily imported products through Atlantic, Mediterranean, Indian Ocean, and Gulf of Guinea gateways; selected local and regional production. Coastal ports to inland agricultural corridors using truck, rail, river, and cross-border wholesale networks. Port warehouses, inland container depots, truck transport, rail corridors, small-scale bagging, and regional distribution centers. Demand is concentrated around rainy-season planting; application rates, affordability, and access to credit strongly affect volume. High long-term potential but constrained by inland freight costs, limited storage, foreign-exchange availability, and fragmented dealer networks. Growth is likely in smaller pack sizes, crop-specific blends, local warehousing, regional trade corridors, and farmer-focused distribution services.
Oceania Import-led agricultural supply market
Highly mechanized farming systems require dependable bulk delivery over long distances.
Urea DAP/MAP Potash Superphosphate Micronutrients Seaborne imports of nitrogen, phosphate, and potash; regional production contributes selected products and soil amendments. Pacific and Indian Ocean shipping routes to coastal terminals, followed by rail and road distribution to grain, pasture, and horticultural regions. Bulk import terminals, inland depots, rail, long-haul trucking, covered storage, and on-farm spreading services. Demand is linked to winter and summer cropping, pasture renovation, rainfall, and commodity prices. Efficient but geographically dispersed network; freight distance, port capacity, and seasonal weather affect delivered cost. Stable demand with increasing interest in soil testing, variable-rate application, controlled-release products, and supply-chain planning.
Data scope: This table presents region-level wholesale distribution characteristics rather than company or brand rankings. “2026 outlook” indicates a forward-looking market direction based on established production capacity, agricultural demand, infrastructure, trade routes, energy exposure, and nutrient-efficiency trends. Reference frameworks include FAOSTAT fertilizer indicators, UN Comtrade trade classifications, International Fertilizer Association market reporting, World Bank commodity-market data, and publicly documented port and logistics patterns. Product availability and trade conditions may vary by country, season, regulation, and contract terms.

Product Categories, Services, and Buyer Requirements

Worldwide fertilizer buyers in 2026 will compare more than price. The International Fertilizer Association’s Medium-Term Fertilizer Outlook expects global nutrient demand to approach 193 million tonnes in 2024/25. This supports steady demand for urea, ammonium products, phosphate fertilizers, potash, NPK blends, and micronutrients. Product fit matters. A high-analysis fertilizer may suit broad-acre crops, while soluble grades support greenhouse fertigation.

Services often separate reliable distributors from simple resellers. Buyers should request batch-specific certificates of analysis, safety data sheets, product registration evidence, and clear origin records. Useful distributors provide custom blending, repacking, port delivery, inland transport, and agronomic guidance. Some also offer soil-testing partnerships and digital shipment tracking. These details reduce surprises when bags arrive damp, labels differ, or delivery windows change.

Buyer requirements should be written before requesting quotations. Specify nutrient percentages, granulation, moisture limits, packaging size, minimum order quantity, Incoterms, destination port, payment terms, and required delivery date. FAO’s fertilizer and soil management guidance repeatedly connects balanced nutrient use with improved efficiency, so buyers should avoid selecting products by nitrogen content alone. A low quoted price can still be expensive. One overlooked requirement, such as a missing import document, may delay an entire shipment. I would also question unusually broad claims about yield improvement. They sound persuasive, but field results depend on soil, crop, weather, and application timing.

Compliance, Sustainability, and Future Trends in Fertilizer Trade

In 2026, leading wholesale fertilizer distributors will compete on compliance as much as price. The International Fertilizer Association projects global fertilizer demand to exceed 205 million tonnes of nutrients by 2028. That growth increases pressure on documentation, quality control, and supply-chain visibility.

Reliable distributors should verify product registration, safety data sheets, batch analysis, and origin records before shipment. Requirements differ across markets, including chemical registration, labeling, customs declarations, and restrictions on nutrient content. A missing laboratory result can delay a container at port. It can also damage a buyer’s crop planning. Strong distributors maintain digital traceability from factory gate to farm delivery.

Sustainability is becoming a purchasing condition, not a public-relations phrase. The OECD-FAO Agricultural Outlook 2024–2033 links future productivity gains with more efficient fertilizer use. Buyers increasingly request nutrient-use efficiency data, lower-emission production evidence, and guidance based on the 4R principles: right source, rate, time, and place. However, carbon figures remain difficult to compare across suppliers. Methods are inconsistent. A polished certificate may hide weak field performance. Distributors should therefore combine lifecycle data with independent testing, farmer feedback, and transparent corrective actions. The best trade networks will invest in cleaner logistics, regional warehousing, and practical agronomic support, while admitting where their evidence is still incomplete.